The Earnest Blog > Managing Student Debt, Student Loan Refinancing
Refinancing federal loans doesn’t mean losing every protection
Spend five minutes in any student loan subreddit and you'll see it happen like clockwork. Someone asks: "Should I refinance my federal loans?" And within minutes, the replies flood in: "NO. Never. You'll lose all your protections."
The advice spreads because it sounds responsible. The problem is it's not entirely true—and for millions of borrowers, believing can be quietly expensive.
The myth that's keeping borrowers from potentially saving money
According to a 2025 Earnest study, only 1 in 10 borrowers1 who could save2 money by refinancing3 actually do.
9 out of 10 eligible borrowers have looked at their loans, imagined everything that could go wrong, and decided to stay put. And while they've been waiting for the worst, the real cost has been compounding. That 1-in-10 statistic isn't a math problem. It's a fear problem.
Taylor, a veterinarian, and Earnest refinancing customer, put it plainly: "My initial concern and hesitation was that my loans would no longer be federally held, meaning I didn't have the backing of the government if anything went substantially wrong with my life financially or anything else."
This hesitation is one of the most common in the country. It also reflects a version of reality that is only partially true.
If someone told you that you could save $6,000 over the life of your loan without changing a single habit, you'd want to know more. The fear of losing "all your protections" is one of the reasons most people say no, and that fear is built on a half-truth.
What you actually give up when you refinance federal loans (and what you don't)
Here's the honest answer: refinancing federal loans into a private loan is a trade-off. And like any financial decision, it depends entirely on your situation. When you make the switch, you lose access to federal income-driven repayment plans like SAVE, PAYE, and IBR, Public Service Loan Forgiveness, and certain federal deferment programs.
For some borrowers, those benefits are worth more than any interest savings. Teachers, government employees, nonprofit workers, and military members actively pursuing PSLF should keep their loans federal—full stop.
But that's not most borrowers. And most borrowers are being told the same thing anyway.
What protections you still get when you refinance with Earnest
This is where the conventional wisdom falls apart.
Refinancing doesn't mean going it alone. What it means, when you refinance with Earnest, is getting set of protections which are more substantial than borrowers realize. Earnest offers a suite of hardship options that rarely get discussed because they're rarely needed.
If you hit a rough patch, here's what's Earnest offers:
Forbearance—temporarily pause your payments if you need a hard stop
Skip-a-payment4—take a one-month breather when a single billing cycle gets tight or for any reason, no questions asked
Interest-only or step payments—temporarily reduce what you owe each month by paying down interest first, or gradually stepping up payments as your income grows
Rate reduction—a temporary reduction to your interest rate and monthly payment amount
Extended term—permanently extend your loan term to lower your monthly payment for the long haul
Rate reduction and extended term—a combination of both, for borrowers who need immediate and lasting relief
Loan discharge—in the event of death or permanent disability
*These options are subject to eligibility requirements and may vary based on individual circumstances and loan terms.
Here's the detail that almost never comes up in those Reddit threads: all of these options except forbearance and skip-a-payment, are specifically designed to prevent negative amortization. In plain terms, negative amortization is what happens when your unpaid interest gets added back onto your loan balance, which means you can make payments every month and still owe more than you started with. Every hardship option on this list except forbearance and skipping a payment keeps that from happening, so even when you're getting relief, you're still making real progress on paying down what you owe. That's a meaningful structural difference that borrowers evaluating the trade-offs deserve to understand.
The worst-case scenarios borrowers are bracing for? There are options available. The scenario they're not accounting for is paying thousands more than they have to because they never refinanced. And that's happening right now, quietly, on every billing cycle.
The real cost of waiting to refinance federal student loans
The numbers are straightforward. On a $50,000 loan, dropping from a 7% fixed rate to 5% over a 10-year term lowers the monthly payment from $581 to $530. Total cost falls from $69,665 to $63,639. That's $6,026 in savings, not from changing spending habits or picking up extra work, but from refinancing.
Every month you wait, that gap widens.
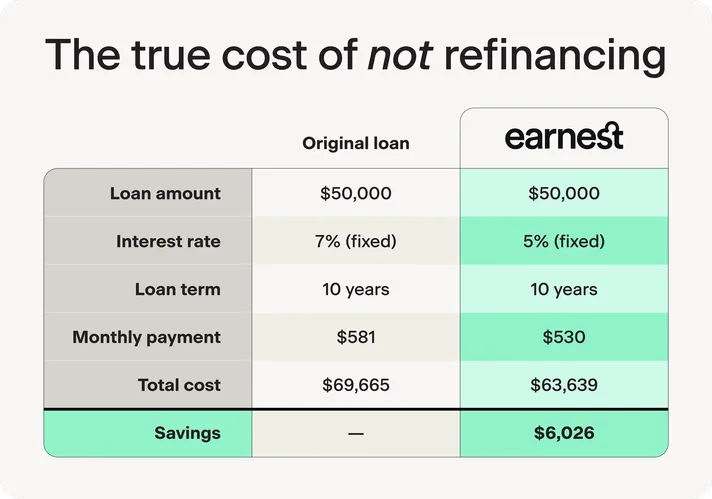
*The example above is for illustration only and may not reflect actual Earnest rates or terms. The example was calculated using the Earnest Student Loan Refinance Calculator. Eligibility and offers depend on your credit profile. Savings are not guaranteed and will vary.
And here's the part that rarely gets said out loud: most borrowers who refinance never end up needing the hardship protections at all. At Earnest, the vast majority of borrowers never use forbearance or hardship options. As of December 2025, 98% of our customers have not used forbearance or hardship options.
The programs exist, they're real, and they're there if life takes a turn, but the overwhelming majority of borrowers who refinance simply make their payments, and pay off their loan.
The irony is stark, as of 2025, data shows federal student loan forgiveness has just an 11.2% acceptance rate, meaning many borrowers are holding out hoping for federal forgiveness protections they statistically won't unlock.
Should you refinance federal loans? A clear framework
Personal finance is personal. There's no universal answer, but there is a clear way to think about it.
Refinancing may make sense if you work in the private sector and aren't pursuing PSLF, have a stable income and don't rely on income-driven repayment, and qualify for a meaningfully lower interest rate. Stick with federal loans if you're on track for PSLF, work in public service or education, or need income-driven repayment flexibility to balance your budget. If you don't fall into those categories—and most borrowers don't—the protections you're holding onto may not actually be protecting you from anything. They may just be costing you.
The bottom line on refinancing federal loans
The advice to 'never refinance federal loans' treats every borrower as if they're the same, and they're not. Yes, refinancing closes certain federal doors. No, it does not leave you without a safety net. And no, the safety net you're giving up is probably not the one you're picturing.
If you're one of the nine borrowers out of 10 who could save money but haven't pulled the trigger, it's worth a second look. Not because refinancing is right for everyone, but because the reason you've been saying no might not hold up under scrutiny.
See what rate you qualify for with Earnest—checking your rate won't affect your credit score.
About the Author
Victoria Holliday
Victoria is the Head of Content at Earnest. She brings extensive ed-tech expertise from six years at Chegg, where she developed educational resources reaching over 20 million students nationwide. With a Master’s in Political Science and experience in public policy from several California campaigns, she’s passionate about creating accessible content that enhances student outcomes in the dynamic world of higher education.
Disclaimer
Disclaimer: This blog post provides personal finance educational information, and it is not intended to provide legal, financial, or tax advice.
1 This claim is based on analysis combining publicly available data and proprietary underwriting models. We applied our proprietary data and underwriting criteria to estimate the portion of borrowers who are credit-eligible and could achieve savings through refinancing. Actual savings and eligibility may vary based on individual circumstances, creditworthiness, and current loan terms. This analysis reflects market conditions as of 2025 and is subject to change.
2 Choosing to refinance to a longer term may lower your monthly payment, but increase the amount of interest you may pay. Choosing to refinance to a shorter term may increase your monthly payment, but lower the amount of interest you may pay. Review your loan documentation for the total cost of your refinanced loan.
3 Please note that you will lose benefits associated with your underlying federal loans, such as federal Income-driven Repayment Plans, Economic Hardship Deferment, Public Service Loan Forgiveness, or other deferment and forbearance options, if you refinance into a private loan. If you file for bankruptcy, you may still be required to pay back this loan.
4 Earnest clients may skip a payment through a one, one-month forbearance during a 12 month period. Your first request to skip a payment can be made once you’ve made at least 6 months of consecutive on-time full principal and interest payments, and your loan is in good standing. The interest accrued during the skipped month will result in an increase in your remaining minimum payment. The final payoff date on your loan will be extended by the length of the skipped payment periods. Any unpaid accrued interest may capitalize (added to the principal balance) at the end of the forbearance period by adding unpaid accrued interest to the outstanding principal as permitted by law and the terms of the loan agreement.
Interest will not be capitalized on loans originated to Michigan residents under the Regulatory Loan Act of 1963. Please be aware that a skipped payment does count toward the forbearance limits. Please note that skipping a payment is not guaranteed and is at Earnest's discretion. Your monthly payment and total loan cost may increase as a result of postponing your payment and extending your term.