The Earnest Blog > Managing Student Debt, Loans
Your guide to pausing student loan payments
This blog contains links to external pages and resources not managed by Earnest
If you need to put your student loan payments on hold, you’ve got a few options to consider. The most common ways to pause your payments are student loan forbearance and student loan deferment, but there are other ways to make your payments more affordable.
Let’s talk about what you can do if you can’t pay and how to pause your student loan payments without hurting your credit.
What’s student loan forbearance?
Student loan forbearance is when your lender gives you a break in payments for a set amount of time. Forbearance is usually capped at 12 months and there’s a limit to how many times you can request it. Federal student loan forbearance stops at 12 months, while private student loan1 forbearance will depend on your lender.

Federal student loan forbearance
There are two types of forbearance available to federal borrowers. There’s general forbearance if you get sick, lose your job, have financial troubles, or have other reasons for needing a break. The second type is mandatory forbearance, which is usually reserved for federal programs, such as AmeriCorps, the National Guard, Medical Residency, and others.
What are the downsides of federal forbearance?
Interest will continue to accrue, making your loan more expensive in the long run
You’ll delay any forgiveness, including Public Service Loan Forgiveness
PSLF and income-driven repayment² forgiveness
It’s a great tool if you don’t have any other options, but it’s got a few limitations. The government will only give you 12 months of forbearance. After that, you have to reapply, and you’re capped at 3 years of forbearance total.
Private student loan forbearance
If you’re interested in forbearance for private student loans, the terms will depend on your lender. Most offer a forbearance program, but they don’t follow the same rules as federal lenders. We recommend checking with your lender about their forbearance program.
At Earnest, we offer up to 12-months of forbearance to help customers who have fallen on hard times. Some reasons our clients could qualify include:
A drop in income
Job loss
A large increase in essential costs (medical expenses, emergency home repairs, or child care)
Unpaid maternity/paternity leave
Like federal forbearance, our forbearance program should be used as a last resort because it could increase your loan and monthly payment. Your interest will continue to accrue and will be added to your loan once your forbearance expires. That’s why we allow you to make payments or cancel your forbearance at any time and return to regular monthly payments.
What’s student loan deferment?
Student loan deferment is another way to put payments on hold. Although it sounds similar to forbearance, it has some key differences.

Federal student loan deferment
Federal deferment is often tied to specific circumstances like returning to school or economic hardship. Those who took out Direct, Federal Family Education Loan FFEL, and Perkins loans can use this program. During deferment, you're not responsible for payments, and in some cases, the government will cover the interest on subsidized loans.
To see if the interest on your loans will be covered, take a look at the chart below.
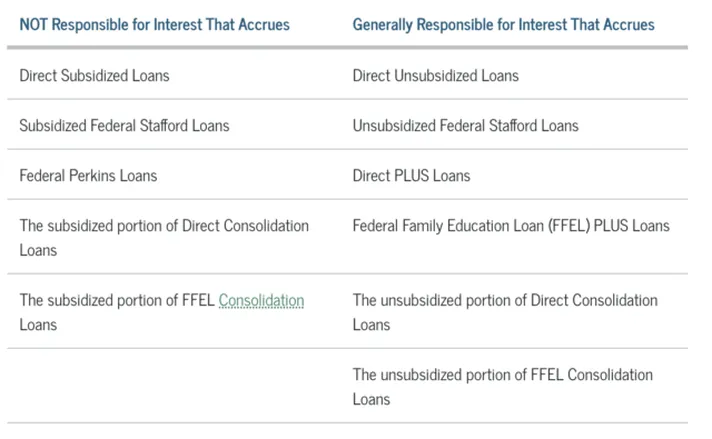 If your interest isn't covered, you’ll have two choices. Either pay the interest as it accrues or wait until your deferral expires. If you choose to wait, your loan will likely increase and could take longer to pay off.
One downside of deferment is that while you’re on it, you won’t be able to progress toward any forgiveness plans, including income-driven repayment and Public Service Loan Forgiveness. You can apply for deferment on studentaid.gov and check their list of valid reasons for deferment.
Private student loan deferment
For private student loans, deferment differs from company to company. You’ll want to visit your lender’s website or call their customer service to find out their policy. You can find a full breakdown of our deferral program on our repayment overview page.
With an Earnest loan, your deferment will depend on your repayment plan. Under some plans, your payment can be fully deferred through a grace period3. Other repayment plans include a minimum payment of $25 or an interest-only payment plan⁴. The best way to find out is to contact our Client Happiness team and they’ll go over your options.
Some downsides of private deferment might be:
Interest will continue to accrue and will be added to your loan
The accruing interest can increase your monthly payment and the total cost of your loan
A larger loan and payment could make it harder to pay off the loan
What are my other options?
There’s a way you could skip payments or pay much less without tapping into emergency programs.
Federal student loan relief
For federal student loans, an income-driven repayment plan might give you the same result as deferment or forbearance. You can sign up for an income-driven repayment directly on studentaid.gov.
Private student loan relief
The first thing you should do is contact your lender. Tell them you need to pause your payments and for how long. They might offer you a new payment plan or other options.
At Earnest, every loan comes with a Skip-A-Payment5 feature in case one of our clients needs a break. It allows all of our customers to skip one payment a year. To qualify, clients must make at least 6 consecutive monthly payments on time and in full. It’s a short-term solution but it can give you temporary relief.
Exploring payment relief
Forbearance and deferment can help you avoid falling behind on payments, but they’re not a magic solution. Before you apply, look into other options, such as income-driven repayment plans. If it’s truly an emergency, these programs can give you a much-needed break and allow you to get back on track with payments.
About the Author
Sasha Bulatskaya
Sasha is the Senior Manager of Brand and Content at Earnest. She has been writing for ten years and has been focused on educational finance and financial aid for over three. Her passion for mission-driven companies brought her to Earnest in 2020, and she's been helping make student finance more accessible ever since. She strives to demystify personal finance and student loans to help borrowers make the best decisions for their financial situation.
Disclaimer
Disclaimer: This blog post provides personal finance educational information, and it is not intended to provide legal, financial, or tax advice.
1 Before applying for private student loans, it’s best to maximize your other sources of financial aid first. It’s recommended to use a 3-step approach to assembling the funds you need: 1) Look for funds you don’t have to pay back, like scholarships, grants, and work-study opportunities. 2) Next, fill out a FAFSA(R) form to apply for federal student loans. Federal Direct subsidized and unsubsidized loans, excluding PLUS Loan for Parents and PLUS Loan for Graduate and Professional Students which require a credit check and a credit worthy endorser if the parent or graduate or professional student has adverse credit, do not require a credit check or cosigner, and offer various protections if you're struggling with your payments. 3) Finally, consider a private student loan to cover any difference between your total cost of attendance and the amount not covered in steps 1 and 2. For more information, visit the Department of Education website at https://studentaid.gov/.
2 As a result of ongoing court actions, the terms of some Income-Driven Repayment (IDR) plans, including the SAVE plan, may be subject to change. Please refer to studentaid.gov for the current status of these plans.
3 Nine-month grace period is not available for borrowers who choose our Principal and Interest Repayment plan while in school.
4 Earnest’s Loan Cost Examples: These examples provide estimates based on principal and interest payments beginning immediately upon loan disbursement. Variable annual percentage rate ("APR"): A $10,000 loan with a 15-year term (180 monthly payments of $152.84) and a 16.85% APR would result in a total estimated payment amount of $27,511.20. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed APR: A $10,000 loan with a 15-year term (180 monthly payments of $152.84) and a 16.85% APR would result in a total estimated payment amount of $27,511.20.
2.) These examples provide estimates based on interest only payments while in school. Variable interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $152.84) and a 16.85% interest rate (16.85% APR) would result in a total estimated payment amount of $35,515.14. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $152.84) and a 16.85% interest rate (16.85% APR) would result in a total estimated payment amount of $35,515.14. Your actual repayment terms may vary. Other repayment options are available. The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $140.42 for 57 months.
3.) These examples provide estimates based on fixed $25 payments while in school. Variable interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $253.39) and a 16.85% interest rate (14.92% APR) would result in a total estimated payment amount of $47,035.20. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $253.39) and a 16.85% interest rate (14.92% APR)would result in a total estimated payment amount of $47,035.20. Your actual repayment terms may vary. Other repayment options are available.The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $25.00.
4.) These examples provide estimates based on deferred payments. Variable interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $275.17) and a 16.85% interest rate (14.67% APR) would result in a total estimated payment amount of $49,530.60. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $275.17) and a 16.85% interest rate (14.67% APR) would result in a total estimated payment amount of $49,530.60. Your actual repayment terms may vary. Other repayment options are available. It is important to note that the 0.25% Auto Pay discount is not available while loan payments are deferred. The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $0.
5 Earnest clients may skip a payment through a one, one-month forbearance during a 12 month period. Your first request to skip a pay can be made once you’ve made at least 6 months of consecutive on-time full principal and interest payments, and your loan is in good standing. The interest accrued during the skipped month will result in an increase in your remaining minimum payment. The final payoff date on your loan will be extended by the length of the skipped payment periods. Any unpaid accrued interest may capitalize (added to the principal balance) at the end of the forbearance period by adding unpaid accrued interest to the outstanding principal as permitted by law and the terms of the loan agreement.