The Earnest Blog > Managing Student Debt, Tutorials & Guides
Student loan consolidation in 2026: Everything you need to know

TL;DR
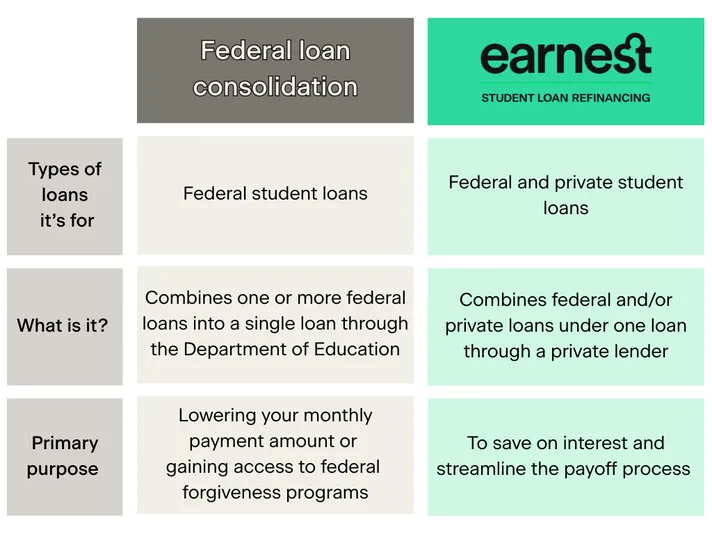
Federal consolidation combines multiple federal loans into a single new loan, often with a longer loan term.
Consolidation can help you lower your monthly payment and gain access to student loan forgiveness.
Unlike student loan refinancing, which is available through private lenders, consolidation is only offered by the federal government.
Consolidation cannot help you lower your interest rate; rate reductions are only possible through refinancing.
Table of Contents
Juggling multiple student loans from different lenders and loan servicers can be complicated to manage—especially if each one has a different payment deadline, interest rate, and loan term. But there are ways to make the process a bit easier, and potentially save you money over time.
One of those methods is student loan consolidation. This is a federal student loan tool that both simplifies your monthly payment and gives you the opportunity to extend your loan term—a move that could dramatically reduce your monthly bill, make it easier to stay on top of your debt, and even help you qualify for some types of student loan forgiveness.
So, how does federal student loan consolidation work? And how is it different from private student loan refinancing¹? Here’s what you need to know.
 Is student loan consolidation the same as refinancing?
While often discussed in the same breath, student loan debt consolidation and refinancing are two very different things. The term “student loan consolidation” usually refers to federal loan consolidation, a U.S. government program that allows borrowers to combine multiple federal education loans into a single new loan. While refinancing is sometimes called “private student loan consolidation,” it’s a very different financial tool. To refinance, you have to go through a private lender—not the federal government.
For the purposes of this article, “consolidation” will always mean federal consolidation, and “refinancing” will always refer to the process of combining loans through a private lender. (More on refinancing later.)
What is student loan consolidation?
Federal student loan consolidation is a tool for reorganizing your federal student loans. When you consolidate, you’ll have the opportunity to streamline your repayment process and simplify your monthly bill. It can also give you the opportunity to change your loan term, choose a different loan servicer, and sign up for federal programs like income-driven repayment plans².
If you choose to extend your loan term during the consolidation process, your new loan could have a lower monthly payment. However, you’ll still have a similar interest rate: with federal loan consolidation, your new rate is just a weighted average of your original rates.
How does student loan consolidation work?
When you consolidate your student loans, the U.S. Department of Education combines all your existing loans for you. Here’s how the process works.
1. Decide which loans you want to consolidate. With federal consolidation, you can elect to consolidate all your federal loans at once, or pick and choose. So, if you have some loans with unique benefits—like a Perkins Loan you think you could get forgiven—you can leave those out. Almost all types of federal loans are eligible for consolidation (but private student loans are not).
2. Start your loan application. Log into your studentaid.gov account to begin the application for a Direct Consolidation Loan. Among other things, the application will ask about your current loans, employment status, any current grace periods, and your preferred loan repayment plan.
2. Pick your plan. Use the Department of Education’s Loan Simulator tool to help you compare plans. Once you know what you want, you can choose your new repayment term (typically between 10 and 30 years) and your new loan servicer. (Note: the one thing you can’t choose is a new interest rate; that’s only available with refinancing.)
3. Submit your application. After you submit your Direct Consolidation Loan application, the Department of Education looks over your personal details. It’ll then let you know if you’re approved.
4. Wait for the government to pay off your current loans. The Department of Education will work with your current loan servicers to pay off your existing student debt. Keep making payments on your old loans until you’re told your consolidation is complete.Once all your old loans are paid off, the Department of Education will issue you a new Direct Consolidation Loan in their stead. Your new loan amount will be a sum of all your previous debts, plus any outstanding interest.
5. Pay off your new loan over time. Once your consolidation is complete, the government will let you know when your first payment is due on your new Direct Consolidation loan. You’ll pay off this balance in a series of monthly installments until the end of your new loan term.
What are the pros and cons of federal consolidation?
Before you consolidate your federal loans, be sure to weigh the benefits and drawbacks.
Pros of federal student loan consolidation
Simplify your bills. With a single loan to worry about, your monthly payments will be simpler and easier to manage.
Reduce monthly payments. Consolidation can lower your monthly bill by extending your repayment term and spreading out your payments over a longer period of time.
Reorganize your debt without a credit check. Most federal student loans are eligible for consolidation—there’s no credit check required.
Unlock income-driven repayment programs. Consolidating certain federal loans—like Parent PLUS Loans—can make them eligible for income-driven repayment (IDR) plans. If you make a certain number of on-time payments under one of these plans, you could have the rest of your debt forgiven.
Choose a new loan servicer. Student loan consolidation lets you choose a new loan servicer from among the federal government’s list of vetted servicers.
Stay eligible for federal borrower protections. You’ll still have access to federal programs like deferment, forbearance, loan forgiveness, and income-driven repayment after you consolidate. (If you refinance through a private lender, on the other hand, you forfeit access to federal forgiveness options and IDR plans.)
Gain access to student loan forgiveness. Federal Family Education Loans and Perkins Loans aren’t eligible for student loan forgiveness programs on their own. However, if you consolidate those loans with other federal debt, your resulting loan could be eligible.
Get out of default. If you’ve defaulted on a loan, federal loan consolidation can provide one avenue for rehabilitating the loan and getting back on track.
Cons of student loan consolidation
You could pay more. If you use consolidation to extend your repayment term, you’ll likely pay more in interest over the life of the loan.
Your principal could increase. When you consolidate, any unpaid interest on your individual loans gets capitalized. In other words, it becomes part of the principal of the new, consolidated loan. So, if you’ve been putting off your interest payments, that could leave you with a bigger balance after you consolidate.
You might lose credit toward forgiveness. Consolidating could reset any progress you’ve made toward loan forgiveness plans like PSLF.
You can’t get a lower interest rate. Your new interest rate will be a weighted average of the interest rates on your current loans—not a revised rate that reflects your current credit score.
You could lose your FFEL rate reduction. Borrowers with loans through the Federal Family Education Loan (FFEL) program can qualify for interest rate reductions. But consolidating FFEL loans turns them into Direct Consolidation Loans—which means forfeiting that rate reduction benefit. If you have FFEL loans, think carefully before consolidating.
What are the alternatives to student loan consolidation?
Student loan consolidation isn’t for everyone. In some cases, you’re better off exploring other solutions. Here are a few common ways to better manage your student loans:
1. Deferment: If you’re between jobs, going back to school, or dealing with financial or medical hardship, you might be able to hit pause on your federal student loans by applying for student loan deferment.
2. Forbearance: Student loan forbearance is similar to deferment, except you’ll have to pay all the interest that accrues during the forbearance period. You also can’t get forbearance for more than a year at a time.
3. Income-driven repayment plans: If you can’t afford the monthly payment on your federal student loans, you may be able to apply for income-driven repayment plans without consolidating first.
4. Student loan settlement: If you default on your loans, you can try contacting your servicer to negotiate new terms of payment.
5. Keeping your current plan: If you don’t qualify for student loan consolidation, don’t want to extend your repayment term, or don’t want to lose the benefits of certain federal loans, it might make sense to stick with your current plan. You can always work toward improving your financial situation and qualifying for refinancing later.
6. Student loan refinancing: Student loan refinancing is similar to consolidation, but it’s done through a private lender. It can help you not only lump your loans into one simple monthly payment but potentially save3 money over the life of your loan.
How is refinancing different from consolidation?
The biggest difference between student loan consolidation and refinancing is that consolidation is only available for federal loans. Student loan refinancing, however, can help you bundle federal loans, private loans, or a mix of loans into a single new loan under a private lender.
The other big difference has to do with interest rates. Unlike consolidation, refinancing involves a credit check. That gives creditworthy borrowers the opportunity to secure a lower interest rate, which could help you save money over the life of your loan.
How does refinancing work?
When you refinance, you first find a private lender—like a bank, credit union, or online lender—who agrees to pay off all your old loans for you. These loans effectively disappear. The lender will then issue a new refinance loan to replace your old debts. This new loan will have a single monthly payment and new loan terms. If you have good to excellent credit, you may also be able to qualify for a lower rate.
If you don’t yet have a strong credit history, you can also choose to refinance with a cosigner. A cosigner can help you gain access to lower interest rates than you’d qualify for on your own.
What are the benefits of a lower interest rate?
If you qualify for a lower interest rate, you can choose to either pay less each month—freeing up room in your budget—or choose or pay down your loan more quickly. The latter option could help you save in interest over the life of the loan.
With refinancing, borrowers can select either a fixed interest rate, or a variable rate, while federal loans (including consolidation loans) are only available at a fixed rate. If you borrowed with a cosigner, you can also release them from the loan obligation when you refinance.
The pros and cons of student loan refinancing
Refinancing is a unique financial tool with serious benefits for certain borrowers. Here are a few of the big ones.
Pros of student loan refinancing
Potential for lower interest rates: If you have a high enough credit score, you may be able to get a significantly lower rate by refinancing through a private lender. Refinancing can be especially handy if you have higher-interest federal loans, like Parent PLUS Loans
Simplified student loan repayment: Refinancing can combine multiple loans of various types into a single loan with a single monthly payment. That can make your bills easier to keep track of and help you avoid missed payments.
Lower monthly payments: By lowering your interest rate and/or extending your repayment term, refinancing can reduce your monthly payment amount, reducing strain on your budget.
More flexible repayment options: Some private lenders, like Earnest, offer custom loan terms, Skip-a-Payment4 programs, and autopay5 discounts.
Pay off debt sooner: If you secure a lower interest rate and choose to keep (or shorten) your repayment term, you may be able to pay off your debt faster. That could save you significant money in interest over time.
Choose between fixed and variable rates: When you refinance, you might be able to switch your loans from a fixed to a variable interest rate, or vice versa. Loans with variable rates generally charge less interest at the outset of the loan, but that rate may increase or decrease over time. Fixed rates, on the other hand, remain the same throughout the life of the loan.
Release a cosigner: If your parents cosigned your loans and they no longer want responsibility for your debt, you can refinance without a cosigner to free them from that risk.
Choose a new loan servicer: Through refinancing you can shop from a wide range of private lenders to find one that’s the right fit for you. (When you consolidate, you can also choose a new servicer, but only from the federal government’s very short list of approved servicers.)
Cons of student loan refinancing
You could lose federal benefits: If you choose to refinance federal student loans with a private lender, they will become private loans. That means you’ll lose access to federal benefits like income-driven repayment plans, loan forgiveness programs, and federal deferment and forbearance options. However, many private lenders offer some forms of relief, such as deferment or forbearance. It can vary by lender so make sure to read the fine print
You’ll need good credit: To qualify for refinancing, you typically need a good credit score and a steady income. If your finances have not improved since you borrowed your original loans, you may not be eligible for favorable refinancing terms.
You may have to pay fees: Some private lenders charge origination fees to take out a refinance loan. (Earnest does not).
Active deferment periods will end immediately: If you are currently in a deferment period—whether that’s your post-graduation grace period or an in-school deferment—that will end as soon as you refinance, and you’ll have to start making payments right away.
Extending your loan term could cost more in interest: If you extend your repayment period to get lower monthly payments, you could end up paying more in interest over the life of the loan. If you keep your loan term the same or shorter, however, you could save money over time.
Should I consolidate or refinance student loans?
Both refinancing and consolidation have distinct benefits and disadvantages. No matter which you choose, it’s important to know that you won’t be able to un-refinance (except for during the three-day “cooling off” period), and you can’t un-consolidate your student debt or send your loans back to their original servicers. Use these guidelines to help make the right decision the first time.
Student loan refinancing may be better for you if…
You have good credit and can qualify for a lower rate
You want a lower monthly payment (and understand that reducing your monthly bill could result in a longer loan term and more interest payments.)
You want to switch to a shorter loan term to get out of debt faster
You don’t expect to need protections offered by the federal government, such as income-based repayment plans
You aren’t serving in the military, working as a teacher, or working a nonprofit or government job that could qualify you for federal loan forgiveness programs
You have only private student loan debt, or you want to combine private and federal student loan debt into a single monthly payment
You want more control over who’s managing your loans
Federal student loan consolidation could be better for you if…
You only have federal student loans
You’re eligible for student loan forgiveness, or think you might be someday
You can’t afford your current monthly payment and think you might qualify for income-driven repayment options
You don’t have a stellar credit score and likely won’t qualify for a lower interest rate through refinancing
You’re in student loan default and want a faster alternative to loan rehabilitation
How do I begin the student loan refinancing process?
The first step to refinancing your student loans is researching your options.
1. Shop around to get rate estimates. Different private lenders offer different interest rates and terms. To see what each can offer, apply for pre-qualification for as many lenders as you can. (Prequalifications use what’s called a “soft credit pull,” which doesn’t hurt your credit score.)
2. Compare annual percentage rates. Comparing annual percentage rates, or APRs, is the best way to compare refinancing offers. That’s because the APR includes the interest rate as well as other fees—giving you a more complete picture of the total cost of the loan. The lower the APR, the better.
3. Consider other perks. APR is important, but it isn’t everything. Some loan servicers offer a kind of signing bonus, called a “student loan refinance bonus,” to entice your business. Others let you choose your own repayment term. Before you pick a private lender to refinance with, look at all these factors. Then, use a student loan refinance calculator6 to estimate the savings possible over the lifetime of your loan.
4. Complete your application. When you’ve settled on a lender, apply for approval. During this step, the lender will perform a credit check. Among other things, they’ll analyze your credit history and score to determine whether you’ll be a responsible borrower.
Get a free rate check from Earnest
Student loan consolidation and refinancing may seem similar, but there are a few key differences. Consolidation is only available for federal loans. It can help you streamline your federal student loan payments and lower your monthly bill, but it can’t help you get a lower interest rate.
On the other hand, student loan refinancing is available for both federal and private student loans. Refinancing can help you lower your interest rate and score new terms, which could save you money over the life of your loan. See what you could be eligible for with a free rate check. It only takes minutes, and it won’t affect your credit score.
Still on the fence? Try out our student loan refinance calculator to see how refinancing could help you meet your personal finance goals.
FAQs
Can I refinance both federal and private student loans?
Yes. Refinancing lets you combine federal, private, or a mix of both loans into one new private loan. Just keep in mind that refinancing federal loans means giving up federal benefits like income-driven repayment and PSLF.
Can I consolidate private and federal student loans together?
No. Federal student loan consolidation is only an option for federal student loans. If you want to combine federal and private loans into one, you’d need to refinance through a private lender.
Will consolidation lower my interest rate?
Not really. Federal consolidation simply averages your existing rates. To potentially get a lower rate, you’d need to refinance with a private lender—though that comes with tradeoffs, like losing federal protections.
Does consolidation affect forgiveness eligibility?
Yes. Federal student loan consolidation can help you qualify for federal programs, such as Public Service Loan Forgiveness (PSLF) if your loans aren’t already Direct Loans (such as FFEL or Perkins). But if your loans are already Direct Loans, consolidation won’t expand your eligibility—and it may reset your progress toward forgiveness.
About the Author
Carolyn Morris
Carolyn is a content marketer and editor who specializes in financial services. With over a decade of experience in the financial services industry, Carolyn has a passion for demystifying the loan application and repayment process for students and their families
Disclaimer
Disclaimer: This blog post provides personal finance educational information, and it is not intended to provide legal, financial, or tax advice.
1 Please note that you may lose benefits associated with your underlying federal loans, such as federal Income-driven Repayment Plans (an example of which is the SAVE plan), Economic Hardship Deferment, Public Service Loan Forgiveness, or other deferment and forbearance options, if you refinance into a private loan. If you file for bankruptcy, you may still be required to pay back this loan.
2 As a result of ongoing court actions, the terms of some Income-Driven Repayment (IDR) plans, including the SAVE plan, may be subject to change. Please refer to studentaid.gov for the current status of these plans.
3 Choosing to refinance to a longer term may lower your monthly payment, but increase the amount of interest you may pay. Choosing to refinance to a shorter term may increase your monthly payment, but lower the amount of interest you may pay. Review your loan documentation for the total cost of your refinanced loan.
4 Earnest clients may skip a payment through a one, one-month forbearance during a 12 month period. Your first request to skip a payment can be made once you’ve made at least 6 months of consecutive on-time full principal and interest payments, and your loan is in good standing. The interest accrued during the skipped month will result in an increase in your remaining minimum payment. The final payoff date on your loan will be extended by the length of the skipped payment periods. Any unpaid accrued interest may capitalize (added to the principal balance) at the end of the forbearance period by adding unpaid accrued interest to the outstanding principal as permitted by law and the terms of the loan agreement.
Interest will not be capitalized on loans originated to Michigan residents under the Regulatory Loan Act of 1963. Please be aware that a skipped payment does count toward the forbearance limits. Please note that skipping a payment is not guaranteed and is at Earnest's discretion. Your monthly payment and total loan cost may increase as a result of postponing your payment and extending your term.
5 You can take advantage of the Auto Pay interest rate reduction by setting up and maintaining active and automatic ACH withdrawal of your loan payment from a checking or savings account. The interest rate reduction for Auto Pay will be available only while your loan is enrolled in Auto Pay. Interest rate incentives for utilizing Auto Pay may not be combined with certain private student loan repayment programs that also offer an interest rate reduction. For multi-party loans, only one party may enroll in Auto Pay.
6 This calculator is a tool to help you visualize repayment options for student loans based on various scenarios provided by you. The information on this page is presented for general personal finance education and it is not intended to provide legal, financial, or tax advice. The accuracy of the calculated results is not guaranteed, and the results are intended for illustrative purposes only. This calculator does not indicate whether you would qualify for an Earnest loan, and the interest rate we approve for you may be higher than the options shown in this calculator if you do qualify. Note that even if you refinance your student loans with Earnest, the outputs of the calculator may not align with loan agreement terms due to several factors, such as your repayment schedule, the interest rate we approve for you, whether you end up choosing a fixed or variable interest rate upon approval, or the timing for sending a payoff to former servicers.