The Earnest Blog > News, Private Student Loans
Earnest Named Best Private Student Loan Lender 2026
This blog contains links to external pages and resources not managed by Earnest.
We’re thrilled to announce that Earnest has been named Best Private Student Loan Lender of 2026 by U.S. News & World Report – for the fourth consecutive year. This recognition reflects our continued commitment to helping students and families confidently finance their education. To date, more than 77,000 students and families, and over 1,300 schools, have trusted Earnest for the flexibility, transparency, and support they deserve.1
Why we stand out
Low interest rates, flexible loan terms, and zero fees
Earnest private student loans can cover up to 100% of your school’s cost of attendance. We offer flexible repayment terms ranging from 5 to 15 years*, so you can choose what works best for you2.
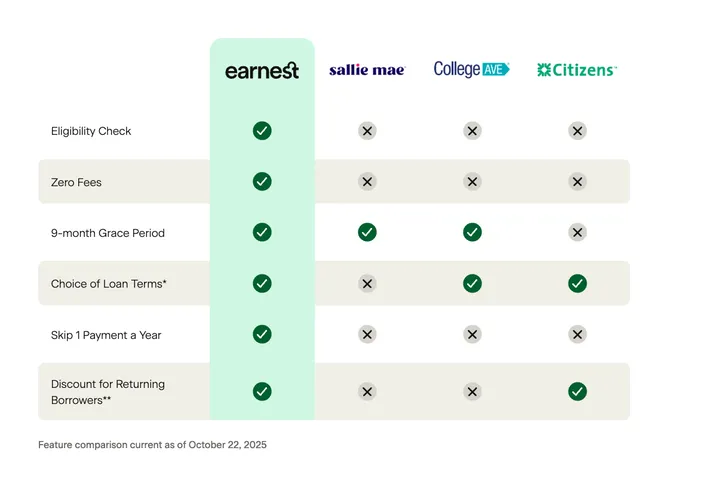
And unlike many lenders, we charge zero fees—no late fees, no origination fees, and no disbursement fees.
Real human support you can count on
Navigating student loans can be overwhelming. That’s why our Client Happiness team is staffed with real people, ready to answer questions, walk through repayment scenarios, and provide support. Contact them over the phone or email.
Life-ready perks
Life doesn’t always go according to plan, and neither should your financial obligations. Earnest continues to offer features that give you breathing room, like:
Skip-a-payment option once per year without fees, so you can manage unexpected expenses.3
A nine-month grace period after graduation (most lenders offer just six).4
Up to 48 months of deferment if you go back to school, start an internship, residency or clerkship.
Continuing to support students and families
We’re always looking for ways to better support students and families on their education journey.
Earlier this year, we removed our minimum income requirement, allowing us to evaluate applicants based on their full financial picture. We also expanded to Nevada, which means we can lend in all 50 states.
And starting in May, Earnest loans will offer cosigner release5, giving cosigners the opportunity to step away from the loan once certain conditions are met.
Lastly, we’ll be rolling out a refreshed application experience later this year. If you’re considering a private student loan, you can check your eligibility in as little as two minutes—without impacting your credit score.
About the Author
Ashley Billing
Ashely Billing writes about finance, work, and wellness, with a focus on practical strategies that can actually help. Drawing on years of experience in content marketing and digital storytelling, she crafts clear, actionable pieces designed to inform and empower readers.
Disclaimer
Before applying for private student loans, it’s best to maximize your other sources of financial aid first. It’s recommended to use a 3-step approach to assembling the funds you need: 1) Look for funds you don’t have to pay back, like scholarships, grants, and work-study opportunities. 2) Next, fill out a FAFSA(R) form to apply for federal student loans. Federal Direct subsidized and unsubsidized loans, excluding PLUS Loan for Parents and PLUS Loan for Graduate and Professional Students which require a credit check and a credit worthy endorser if the parent or graduate or professional student has adverse credit, do not require a credit check or cosigner, and offer various protections if you're struggling with your payments. 3) Finally, consider a private student loan to cover any difference between your total cost of attendance and the amount not covered in steps 1 and 2. For more information, visit the Department of Education website at https://studentaid.gov/.
Earnest Private Student Loans are subject to credit approval.
Earnest clients may skip a payment through a one, one-month forbearance during a 12 month period. Your first request to skip a pay can be made once you’ve made at least 6 months of consecutive on-time full principal and interest payments, and your loan is in good standing. The interest accrued during the skipped month will result in an increase in your remaining minimum payment. The final payoff date on your loan will be extended by the length of the skipped payment periods. Any unpaid accrued interest may capitalize (added to the principal balance) at the end of the forbearance period by adding unpaid accrued interest to the outstanding principal as permitted by law and the terms of the loan agreement.
Nine-month grace period is not available for borrowers who choose our Principal and Interest Repayment plan while in school.
To request cosigner release, the primary borrower must have made 12 consecutive, monthly on-time principal and interest payments (or an amount equal thereto) immediately preceding the cosigner release application. The primary borrower must satisfy certain eligibility and credit criteria at the time of application. Additional terms and conditions apply. To qualify for automatic cosigner release, the outstanding principal balance of your loan must be paid down to 50% or less of the original principal balance. The primary borrower must have made 36 months of required payments after the end of the Interim Period. The primary borrower must meet our eligibility and minimum credit requirements. Additional terms and conditions may apply.
* Available interest rates are subject to change. Interest rates as of 03/19/2026. Earnest’s Loan Cost Examples: 1.) These examples provide estimates based on principal and interest payments beginning immediately upon loan disbursement. Variable annual percentage rate ("APR"): A $10,000 loan with a 15-year term (180 monthly payments of $152.84) and a 16.85% interest rate without Auto Pay (16.85% APR) would result in a total estimated payment amount of $27,511.20. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed APR: A $10,000 loan with a 15-year term (180 monthly payments of $150.30) and a 16.49% interest rate without Auto Pay (16.49% APR) would result in a total estimated payment amount of $27,054.10. 2.) These examples provide estimates based on interest-only payments while in school. Variable interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $152.84) and a 16.85% interest rate without Auto Pay (16.85% APR) would result in a total estimated payment amount of $35,515.14. For a variable loan, after your starting rate is set, your rate will then vary with the market. Your actual repayment terms may vary. Other repayment options are available. The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $140.42 for 57 months. Fixed interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $150.30) and a 16.49% interest rate without Auto Pay (16.49% APR) would result in a total estimated payment amount of $34,886.94. Your actual repayment terms may vary. Other repayment options are available. The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $137.42 for 57 months. 3.) These examples provide estimates based on fixed $25 payments while in school. Variable interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $253.39) and a 16.85% interest rate without Auto Pay (14.92% APR) would result in a total estimated payment amount of $47,035.20. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $246.61) and a 16.49% interest rate without Auto Pay (14.65% APR) would result in a total estimated payment amount of $45,814.80. Your actual repayment terms may vary. Other repayment options are available. The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $25.00. 4.) These examples provide estimates based on deferred payments. Variable interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $275.17) and a 16.85% interest rate without Auto Pay (14.67% APR) would result in a total estimated payment amount of $49,530.60. For a variable loan, after your starting rate is set, your rate will then vary with the market. Fixed interest rate: A $10,000 loan with a 15-year term (180 monthly payments of $268.03) and a 16.49% interest rate without Auto Pay (14.39% APR) would result in a total estimated payment amount of $48,245.40. Your actual repayment terms may vary. Other repayment options are available. It is important to note that the 0.25% Auto Pay discount is not available when the deferred repayment option has been selected and the loan is in the interim period. The calculation assumes that the “in-school” period is 4 years (48 months) and includes our 9 month grace period, during which the monthly payment will be $0.
** To be eligible for the Loyalty Discount, applicants must have previously obtained an Earnest Private Student Loan and apply using the same email address associated with that loan. Only one Loyalty Discount may be applied per eligible Earnest Private Student Loan. Not all applicants may qualify. This offer cannot be combined with Earnest’s Rate Match program. Earnest may modify or discontinue this offer at any time and without notice, however, once a loyalty discount is earned, it will not be taken away.