Medical loans from $3,000–$50,000
Whether you’re covering large hospital bills or a last-minute procedure, see how you could save with exclusive perks for eligible borrowers:
No fees required: No prepayment, late, or mandatory origination fees
Rate Drop Reward: Lower your rate by up to 0.75% as you reach certain repayment milestones2
Skip 1 payment a year: No penalty fees, just breathing room3
Get your funds in as little as 24 hours: For one less thing to stress about4
What is a medical loan?
A medical loan is a personal loan used to cover healthcare expenses that aren’t fully paid for by insurance or aren't covered at all. From unexpected emergency bills to planned procedures, a medical loan could give you upfront funds that you repay over time in fixed monthly payments. Compared to many high-interest credit cards, medical loans may come with lower, more affordable interest rates.
You could save thousands in interest with an Earnest Personal Loan
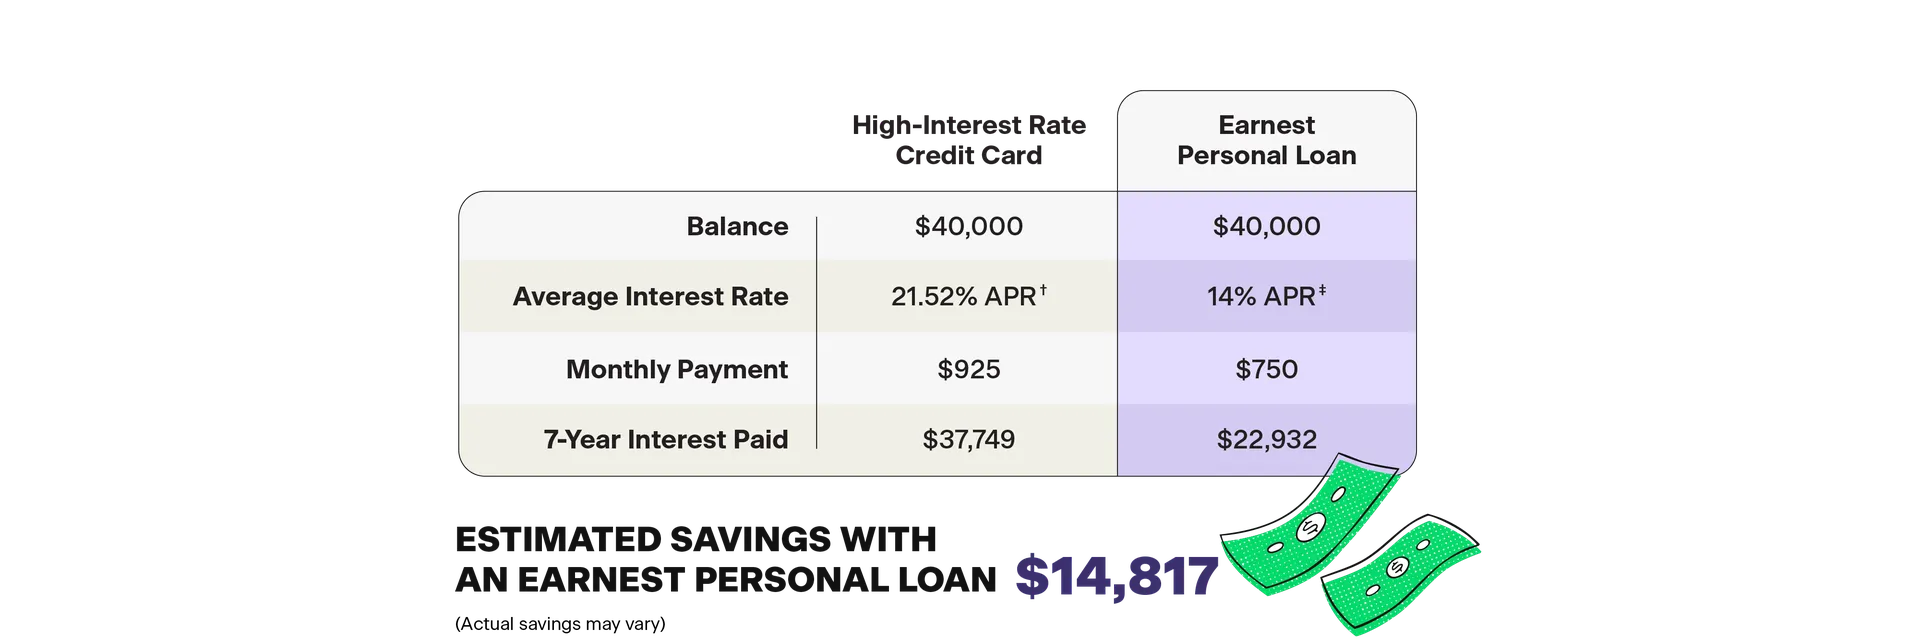
† Average credit card annual percentage rates (APR) are accurate as of the Federal Reserve G.19 release on 04/07/2026 (reflecting data from February 2026). Source: https://www.federalreserve.gov/releases/g19/current/
‡ Example chart reflects a 7-year Earnest Personal Loan with a fixed rate of 14% APR (the mid-range of rates as of April 2026). Earnest Personal Loans are subject to credit approval; available rates are subject to change and exclude any discounts. The 'High-Interest Rate Credit Card' APR of 21.52% is the average rate reported for February 2026. Savings estimates assume you make all payments on time as scheduled for 84 months, without taking on additional credit card debt. The calculation also assumes no origination fees or early prepayments.
Rate Drop Reward: Only with Earnest
You could lower your interest rate by up to 0.75% as you pay down your loan on time each month. Say you start with a 10% fixed interest rate—you could qualify for a rate as low as 9.25% once you've paid off 75% of your loan. The result? You’ll pay less interest overall. It's our way of rewarding responsible repayment, not just collecting payments.
What can I use a medical loan for?
Because a medical loan is a type of personal loan, you can use it for almost any personal or medical purpose. Borrowers often use medical loans to cover:
Elective medical procedures
Cosmetic surgery
IVF treatments
Emergency medical treatments
Travel to or from the clinic
Recovery costs
You can also use a medical loan to cover medical costs associated with routine procedures. However, if you can’t afford your medical bills, it’s best to ask your healthcare provider if they can offer you a financial assistance package first.
How it works

Check your rate in minutes
Zero credit score impact

Submit your application
3 simple steps and only takes minutes

Customize your loan
Choose from up to 72 payment options
FAQs about medical loans
Have more questions? Visit the Resource Center.
From the Earnest Blog
Tips and tools for managing your medical loan
Disclaimer: This page provides personal finance educational information, and it is not intended to provide legal, financial, or tax advice.
1 You may qualify for a lower interest rate by electing to pay an optional origination fee that is equal to 1-8% of your total loan amount. The fee is deducted from your loan proceeds at disbursement. This fee is not required and it will not impact your loan approval.
2 You may be eligible for up to a 0.75% interest rate reduction, earned in 0.25% increments, by meeting the following milestones:
• 25% of your loan principal is repaid and you make at least 12 consecutive on-time monthly payments
• 50% of your loan principal is repaid and you make an additional 12 consecutive on-time monthly payments since the prior rate reduction
• 75% of your loan principal is repaid and you make an additional 12 consecutive on-time monthly payments since the prior rate reduction
Rate reductions are applied automatically once earned. Lump-sum payments cannot accelerate the timing of discounts.
3 Earnest clients may skip a payment through a single, one-month deferment during a 12-month period. Your first request to skip a payment can be made once you’ve made at least 6 months of consecutive on-time full principal and interest payments, and your loan is in good standing. The interest accrued during the skipped month will result in an increase in your remaining minimum payment. The final payoff date on your loan will be extended by the length of the skipped payment periods.
4 24 hour funding is not guaranteed and is subject to the availability of funds which includes but is not limited to the time of loan approval, verification requirements, and bank processing times.